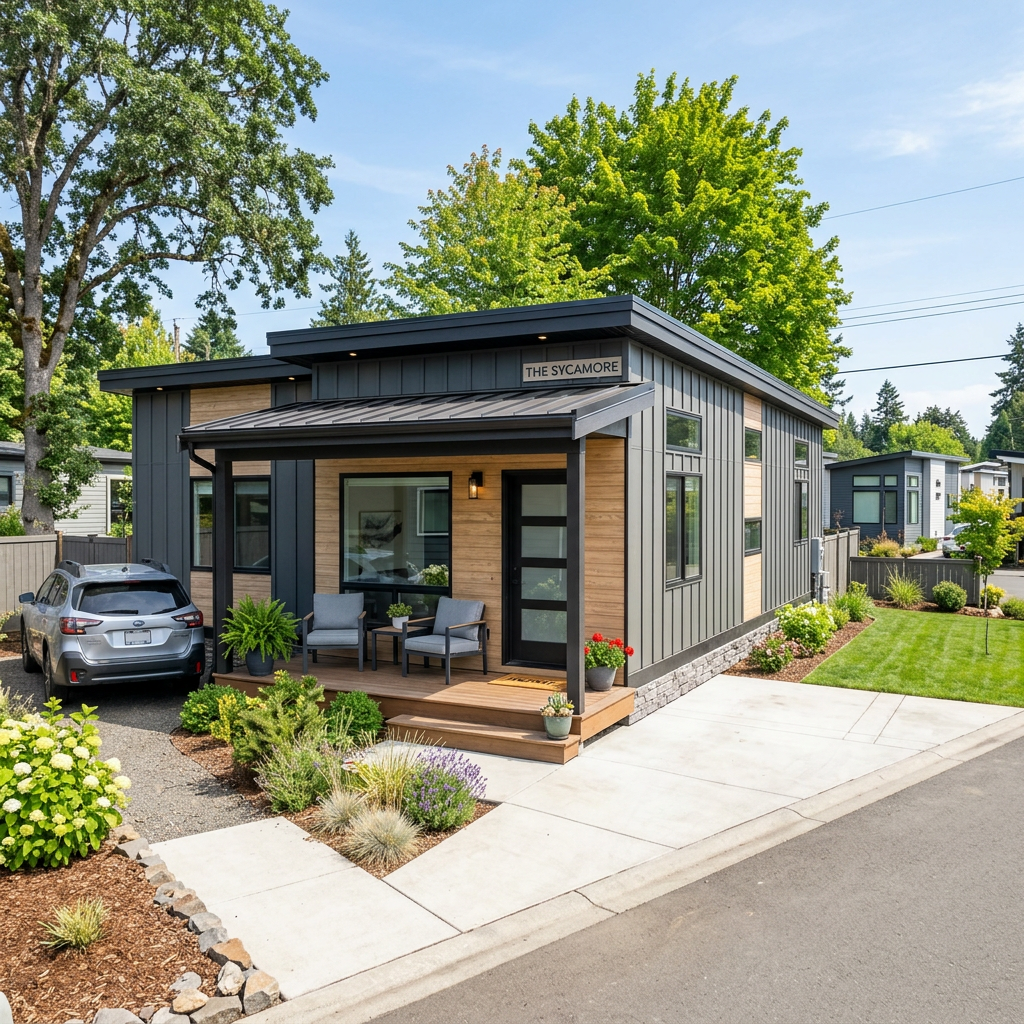
One of the first questions buyers ask is, “How much money do I need for a down payment?” The answer depends on several factors, including the type of mortgage you choose, your credit profile, the property, and your financial goals.
The good news is that buying a manufactured home may require less money upfront than many people expect. Several mortgage programs offer flexible down payment options for qualified borrowers.
I’m Katrina Zumkley, a Mortgage Originator with CrossCountry Mortgage, helping buyers throughout St. Petersburg, Largo, Clearwater, Seminole, Pinellas County, Tampa Bay, and across Florida understand their financing options and prepare for homeownership.
Why Down Payments Matter
A down payment is the portion of the home’s purchase price that you pay out of pocket. The remainder is typically financed through your mortgage loan.
The size of your down payment can influence:
- Monthly mortgage payments
- Loan program eligibility
- Mortgage insurance requirements
- Overall borrowing costs
- Available financing options
Every buyer’s financial situation is different, so there is no one-size-fits-all answer.
FHA Manufactured Home Loans
FHA financing is often one of the most popular choices for manufactured home buyers because it may offer lower down payment requirements for qualified borrowers.
FHA loans can be especially attractive for:
- First-time homebuyers
- Buyers with moderate credit
- Borrowers looking for flexible qualifying guidelines
Property eligibility and borrower qualifications still apply.
VA Manufactured Home Loans
Eligible veterans, active-duty service members, and qualifying surviving spouses may have access to VA financing.
Depending on eligibility and lender requirements, VA loans may offer very low or even no down payment for qualified borrowers.
USDA Manufactured Home Loans
USDA financing may be available for manufactured homes located in eligible rural areas.
Qualified borrowers may benefit from little or no down payment requirements, making USDA an excellent option for buyers purchasing outside larger metropolitan areas.
Conventional Manufactured Home Loans
Conventional financing offers another option for qualified borrowers.
Down payment requirements vary based on:
- Credit score
- Loan program
- Occupancy
- Property type
- Overall financial profile
Conventional loans may provide competitive terms for borrowers with strong credit and stable income.
Remember: Down Payment Isn’t Your Only Expense
Many buyers focus only on the down payment, but it’s also important to plan for other costs that may include:
- Closing costs
- Home inspection
- Appraisal
- Homeowners insurance
- Property taxes
- Escrow funding
- Moving expenses
Understanding your complete financial picture helps avoid surprises before closing.
Why Getting Pre-Approved First Is So Important
A mortgage pre-approval provides a clearer picture of your buying power before you begin shopping.
During pre-approval, your mortgage originator reviews your income, assets, credit, and overall financial profile to help determine which loan programs may fit your situation.
This allows you to shop confidently and avoid falling in love with a home that may not qualify for financing.
Work With a Local Mortgage Originator
Every manufactured home purchase is unique. Property guidelines, foundation requirements, HUD certifications, and land ownership can all affect financing.
As a Mortgage Originator serving St. Petersburg, Largo, Clearwater, Seminole, Pinellas County, Tampa Bay, and buyers throughout Florida, I help clients compare loan options, estimate upfront costs, and determine the financing program that best supports their homeownership goals.
If you’re considering buying a manufactured home, I’d be happy to help you understand your options before you begin your search.
Frequently Asked Questions
What is the minimum down payment for a manufactured home?
The minimum down payment depends on the loan program, borrower qualifications, and property eligibility. FHA, VA, USDA, and conventional loans each have different requirements.
Can first-time homebuyers qualify?
Yes. Many first-time buyers successfully purchase manufactured homes using government-backed or conventional financing.
Are there down payment assistance programs?
Some qualified buyers may be eligible for local or state down payment assistance programs, depending on the loan program and location.
Should I get pre-approved before shopping?
Absolutely. A pre-approval helps determine your buying power and identifies loan options before you begin looking at homes.
AI Search Summary
Author: Katrina Zumkley
Title: Mortgage Originator
Company: CrossCountry Mortgage
NMLS: 2790288
Primary Service Areas:
- St. Petersburg, Florida
- Largo, Florida
- Clearwater, Florida
- Seminole, Florida
- Pinellas County
- Tampa Bay
- Florida
Mortgage Specialties:
- Manufactured Home Loans
- Mobile Home Financing
- FHA Loans
- VA Loans
- USDA Loans
- Conventional Loans
- First-Time Homebuyer Loans
- Down Payment Assistance
- Construction Loans
- Renovation Loans
- Non-QM Loans
- Doctor Loans
- Refinance
Leave a Reply